Ключевые факты
- Даты
- 8–12 мар. 2027 (5 дней)
- Где
- Pacific Regency Hotel Suites, Куала-Лумпур, Малайзия
- Стоимость на одного участника
- £3 140 (GBP)
- Оплата
- По счету банковским переводом
- Регистрация закрывается
- 17 янв. 2027
- Формат
- 5-day short course: a practical capacity-building programme for government, NGO and project teams in Kuala Lumpur
- Корпоративный формат
- Проведите ее для своей команды в удобные вам даты
На этой странице 10 разделов
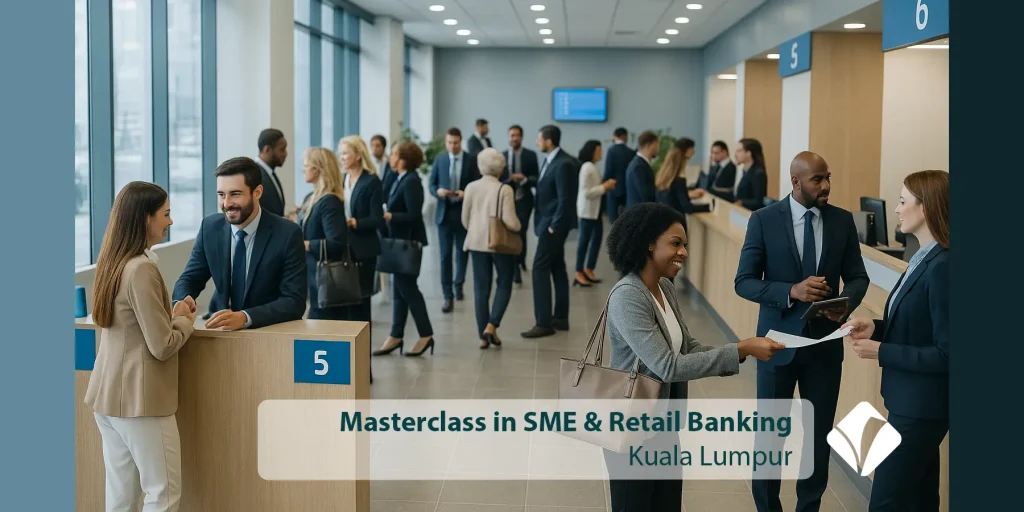
Мастер-класс по банковскому обслуживанию МСП и розничному банкингу в Куала-Лумпуре
Обзор программы
Small and medium enterprises and retail customers are the core franchise of most commercial banks, yet they remain the hardest segments to serve profitably. SMEs need fast decisions, flexible products and advice; households expect digital service at low cost. Banks that combine sound credit risk management with good segmentation and efficient channels grow these books safely; those that do not face rising losses or lose customers to new competitors. The financing need is large: an IFC estimate published on the SME Finance Forum in February 2026 puts the finance gap for formal micro, small and medium enterprises in 119 emerging and developing economies at USD 5.7 trillion, about 19% of their combined GDP, with a further USD 2.1 trillion of potential demand from informal firms. IFC notes that MSMEs make up over 90% of firms worldwide and about 70% of employment.
Malaysia shows how a banking system can respond. According to Bank Negara Malaysia’s 2025 Annual Report, banks and development financial institutions approved RM186.7 billion in new SME financing in 2025 across more than 206,000 accounts, and outstanding SME financing grew 5.9%. The central bank’s SME funds have disbursed RM29.3 billion to 82,714 SMEs since 2020, and from 2026 the funds are moving from direct lending to a guarantee model. Competition is also changing: Bank Negara Malaysia awarded five digital bank licences in April 2022, three conventional and two Islamic, under its Financial Sector Blueprint 2022–2026. By the end of 2025 all five were operating, serving 2.4 million customers, about 65% of them from unserved or underserved segments.
This Masterclass in SME & Retail Banking in Kuala Lumpur brings these strands together over five days: retail banking products and operations, SME segmentation and value propositions, SME credit risk and pricing, prudential and accounting requirements, and digital and open finance. Each day uses Malaysian and international cases and ends with a practical workshop.
Программа укрепляет институциональный потенциал в следующих областях:
- Стратегия розничного банкинга, продукты и операционные модели
- Deposit, savings and transaction product design
- Retail lending products and responsible lending
- Открытие счетов, комплексная проверка клиентов и подключение
- Нефондовые услуги и комиссионный доход
- Funding and liquidity considerations for retail and SME books
- SME market segmentation and value propositions
- SME product and service development
- Relationship management and sales delivery for SMEs
- Оценка кредитоспособности МСП с использованием финансовых и альтернативных данных
- Ценообразование по кредитам МСП на основе оценки рисков
- Credit guarantees and risk-sharing arrangements
- Expected credit loss provisioning for SME portfolios
- Capital treatment of SME and retail exposures
- Portfolio monitoring and early warning systems
- Branch, digital and partner distribution channels
- Mobile, QR and digital payment services
- Партнерство в сфере открытых данных и открытых финансов
- Islamic and value-based SME financing
- Sustainable and transition finance for SMEs
- Key performance targets and profitability analysis
- Customer experience and complaint handling
Why this matters now
Организациям все больше нужны специалисты, способные:
- Segmenting SME and retail customers by need, risk and value
- Designing products that fit cash-flow patterns of small firms
- Оценка кредитоспособности малого и среднего бизнеса при ограниченной финансовой отчетности
- Using alternative and transaction data responsibly
- Pricing loans to cover risk, capital and operating cost
- Structuring guarantees and risk-sharing with public schemes
- Calculating and explaining expected credit losses
- Managing digital onboarding and customer due diligence
- Построение партнерских отношений с финтех-компаниями и платформами
- Мониторинг портфелей и реагирование на сигналы раннего предупреждения
- Measuring branch and channel profitability
- Managing Islamic and value-based financing products
- Reporting SME lending results to boards, regulators and financiers
Strong SME and retail banking systems help organisations:
- Grow lending while keeping non-performing loans under control
- Снижение затрат на обслуживание за счет цифровых каналов
- Raise fee and deposit income from SME customers
- Эффективное использование гарантий и кредитных линий
- Соответствие нормативным требованиям, ожиданиям в отношении капитала и раскрытия информации
- Охват недостаточно обслуженных клиентов и регионов
- Retain customers facing new digital competitors
- Show measurable development impact to financing partners
- Support climate resilience and sustainable investment by small firms
- Сбор
- Очистка
- Хранение
- Анализ
- Решение
Кому стоит участвовать
Программа предназначена для:
- Bank, branch and general managers
- Heads and senior professionals in SME banking
- Heads and senior professionals in retail and consumer banking
- Digital banking and channel managers
- Credit risk managers and credit analysts
- Relationship managers for SME clients
- Product development managers
- Customer experience and transformation professionals
- Sales professionals and training managers
- Heads of marketing and marketing managers
- Strategic planning staff and financial analysts
- Staff of development financial institutions
- Officers of credit guarantee corporations and schemes
- Central bank and regulator staff working on SME finance and inclusion
- Managers of donor-funded SME credit lines and project implementation units
- Microfinance and Islamic finance managers
- Fintech partnership and open banking leads
Отметьте, что должна уметь ваша команда.
Цели программы
По завершении программы участники смогут:
- Разъяснение роли, структуры и регулирования розничного и малого и среднего банкинга
- Design deposit, lending and fee-based products for target segments
- Segment the SME market and build value propositions for each segment
- Assess SME credit using financial, cash-flow and alternative data
- Price SME loans using risk, capital and cost components
- Применение стадий ожидаемых кредитных убытков к портфелям МСП
- Use credit guarantees and risk-sharing to extend lending
- Plan branch, digital and partner distribution channels
- Evaluate open finance and fintech partnership models
- Set key performance targets and analyse SME profitability
- Оценка будущих тенденций в сфере малого и среднего бизнеса и розничного банкинга
- Подготовка бизнес-плана МСП-банкинга для своего учреждения
Training Structure & Contents
- The definition, role, types and management structures of retail banks
- Regulation, reporting and principles of retail banking operations
- Deposit-taking, savings products and liquidity considerations
- Account opening, onboarding journeys and customer due diligence
- Retail lending products, non-fund-based services and responsible lending
- Funding sources, liquidity management and operational best practices
- Workshop: Diagnosing a Retail Product Portfolio for value, margins and onboarding efficiency
- Principles, key elements and definitions of SME and micro-enterprise banking
- Segmenting the SME market by size, sector and business life cycle
- Addressing technical and political aspects of SME segmentation
- Identifying SME requirements across working capital, investment, trade and payments
- SME product and service development, including non-financial advisory
- Islamic and value-based SME banking products and international benchmarks
- Case Study: Malaysia’s SME Financing Ecosystem and the shift to guarantee models
- Credit risk management and financial analysis with limited financial statements
- Cash-flow, transaction-based assessments and alternative data scoring models
- Use of collateral, movable assets, guarantees and risk-sharing arrangements
- Risk-based loan pricing covering risk, capital, funding and operating costs
- Expected credit loss staging and capital treatment of SME and retail exposures
- Portfolio monitoring, early warning indicators, restructuring and recovery
- Workshop: Pricing and Provisioning an SME Loan Book under guarantee scenarios
- Operating retail distribution channels, branch transformation and cost-to-serve analysis
- Mobile and internet banking solutions alongside QR and instant merchant payments
- Malaysian digital bank operational models, licensing and market outcomes
- Open data, data-sharing standards, consent frameworks and fintech partnerships
- Designing digital lending journeys for small firms and embedded finance models
- Managing cyber, fraud and operational risks in digital distribution
- Case Study: Customer acquisition and journey design lessons from Malaysian digital banks
- Measuring SME banking business performance and channel profitability
- Setting key performance targets and tracking portfolio health
- Evaluating future trends, digital disruption and open finance developments
- Integrating Islamic and sustainable transition finance for small firms
- Governance, board reporting and regulatory disclosure standards
- Synthesising strategy, credit, products and digital delivery
- Workshop: Developing an integrated SME banking business plan
Полное содержание по дням
First Day | Retail Banking Foundations and Operating Models
- The definition, role, types and management structures of retail banks
- Regulation, reporting and principles of retail banking operations
- Deposit-taking, savings products and liquidity considerations
- Account opening, onboarding journeys and customer due diligence
- Retail lending products, non-fund-based services and responsible lending
- Funding sources, liquidity management and operational best practices
- Workshop: Diagnosing a Retail Product Portfolio for value, margins and onboarding efficiency
Second Day | SME Segmentation, Products and Value Propositions
- Principles, key elements and definitions of SME and micro-enterprise banking
- Segmenting the SME market by size, sector and business life cycle
- Addressing technical and political aspects of SME segmentation
- Identifying SME requirements across working capital, investment, trade and payments
- SME product and service development, including non-financial advisory
- Islamic and value-based SME banking products and international benchmarks
- Case Study: Malaysia’s SME Financing Ecosystem and the shift to guarantee models
Third Day | SME Credit Risk, Pricing and Provisioning
- Credit risk management and financial analysis with limited financial statements
- Cash-flow, transaction-based assessments and alternative data scoring models
- Use of collateral, movable assets, guarantees and risk-sharing arrangements
- Risk-based loan pricing covering risk, capital, funding and operating costs
- Expected credit loss staging and capital treatment of SME and retail exposures
- Portfolio monitoring, early warning indicators, restructuring and recovery
- Workshop: Pricing and Provisioning an SME Loan Book under guarantee scenarios
Четвертый день | Цифровые каналы, цифровые банки и открытые финансы
- Operating retail distribution channels, branch transformation and cost-to-serve analysis
- Mobile and internet banking solutions alongside QR and instant merchant payments
- Malaysian digital bank operational models, licensing and market outcomes
- Open data, data-sharing standards, consent frameworks and fintech partnerships
- Designing digital lending journeys for small firms and embedded finance models
- Managing cyber, fraud and operational risks in digital distribution
- Case Study: Customer acquisition and journey design lessons from Malaysian digital banks
Fifth Day | Performance, Future Strategy and the Business Plan
- Measuring SME banking business performance and channel profitability
- Setting key performance targets and tracking portfolio health
- Evaluating future trends, digital disruption and open finance developments
- Integrating Islamic and sustainable transition finance for small firms
- Governance, board reporting and regulatory disclosure standards
- Synthesising strategy, credit, products and digital delivery
- Workshop: Developing an integrated SME banking business plan
Методология обучения
The masterclass uses an applied learning approach combining interactive lectures, Malaysian and international case studies, and daily practical exercises. Every objective is applied in a structured workshop using realistic portfolio data, enabling direct transfer of tools and frameworks to participants’ home institutions.
- Interactive presentations covering regulatory, credit and operational principles
- Group diagnostic exercises using bank product portfolios, margins and cost data
- Portfolio modelling workshops on loan pricing, provisioning and guarantees
- Analysis of real-world market cases from digital banks and guarantee schemes
- Collaborative strategy sessions requiring cross-functional alignment on SME business plans
Ожидаемые результаты
- Structured capability to design, price and distribute SME and retail banking products
- Practical competence in applying alternative data and cash-flow assessments to SME underwriting
- Ability to model risk-based loan pricing and calculate expected credit loss provisions
- Clear frameworks to evaluate digital bank competition, fintech partnerships and open finance
- Formulation of a comprehensive SME banking business plan tailored to institutional objectives
£3 140 за участника · оплата по счету банковским переводом · для групп от 5 человек предусмотрена скидка
Пять и более участников от одной организации: укажите групповой тариф в запросе счета.
Ten or more: an in-house version for your institution may cost less per person. Ask for an in-house quote.
Registration closes in 56 days (17 Jan 2027)
Who Will Deliver This Programme
Each date is delivered by a team assigned from Risalat's expert network for this subject. For this programme we assign:
How we choose them: Experience in the region of the participants or comparable settings; Command of the financier rules that apply (World Bank, ADB, AfDB, EU, UN) where relevant; Delivery in English; other languages on request for in-house groups; No conflict of interest with participants' institutions.
Training courses in Kuala LumpurУчебные курсы по банковскому делу и страхованию
Источник: Департамент статистики Малайзии, показатели МСП 2025
1. What is IFC's latest estimate of the formal MSME finance gap in emerging and developing economies?
An IFC estimate published by the SME Finance Forum in 2026 puts the formal MSME gap at USD 5.7 trillion across 119 economies.
2. What share of Malaysia's digital bank customers came from unserved or underserved segments by end-2025?
В годовом отчете Bank Negara Malaysia за 2025 год указано, что около 65% из 2,4 миллиона клиентов цифровых банков не были охвачены банковскими услугами или испытывали их недостаток.
3. How is Bank Negara Malaysia changing its SME funds from 2026?
В годовом отчете Bank Negara Malaysia за 2025 год указано, что фонды для малого и среднего бизнеса перейдут от прямого кредитования к модели гарантий с 2026 года.
Почему эта программа проходит в Куала-Лумпуре
Куала-Лумпур сочетает доступные цены, упрощенный визовый режим для многих стран и примеры работы подразделений по обеспечению результатов в госсекторе.
The Masterclass in SME & Retail Banking in Kuala Lumpur programme in March 2027 brings together officials and professionals from across the Asia region and beyond. Sessions combine short inputs, case studies and group work on participants' own files, and the city's institutions can be added as a study visit on request.
Как добраться: Международный аэропорт Куала-Лумпура (KUL).
Узнайте, нужна ли вам виза, с помощью бесплатного сервиса «Проверка визы» и запросите приглашение после регистрации.
Та же тема в других городах
- Public Sector Fiber Backbone Contracting and Open Access Regulation in Casablanca (Casablanca)
- Affordable Mortgage Finance Expansion & Capital Market Instruments in Nairobi (Nairobi)
- Обучение по исламскому банкингу, финансам и финансовым услугам, соответствующим нормам шариата (Стамбул)
Другие программы в Куала-Лумпуре
- Carbon Accounting and Net-Zero Planning for Institutions in Kuala Lumpur
- AI for Public Financial Management and Audit Training in Kuala Lumpur
- Occupational Health and Safety Management on Public Works Contracts in Kuala Lumpur
- Public Administration Reform and Civil Service Management in Kuala Lumpur
- Public Hospital Infectious Disease Infrastructure & Biosafety in Kuala Lumpur
См. также: Программы развития предпринимательства и МСП · бесплатная оценка потребностей в обучении · все программы
Teams often travel here from Timor-Leste, Maldives, Sri Lanka, Bangladesh, Nepal, Bhutan, Pakistan, Myanmar. Funding, visa letters and group rates are explained on each country page.
Is there banking and financial sector training for government officials in Kuala Lumpur in March 2027?
Can "Masterclass in SME & Retail Banking in Kuala Lumpur" be delivered in-house for one organisation?
Какие еще программы по банковскому и финансовому сектору проводит Risalat?
Как организации регистрируются и оплачивают участие?
Для команд и организаций
Bring your team
Teams that learn together apply more at work. Tell us how many people and how you would like to take part: we reply with a group quote within two working days.
Watch: this programme in short



Другие учебные курсы в Малайзии · Все программы в Азии · Полный календарь обучения
Запланировать эту программу в дорожной карте: почему это важно, зачем это утверждать, даты планирования и карьера, которую это создает.