关键信息
- 日期
- 2027年2月15–19日(5天)
- 地点
- 格鲁吉亚第比利斯Regus Tbilisi - Vazha Pshavela
- 每位学员费用
- £2,880(英镑)
- 付款
- 通过发票和银行转账付款
- 报名截止
- 2027年1月6日
- 形式
- 5-day short course: a practical capacity-building programme for government, NGO and project teams in Tbilisi
- 证书
- 结业证书
- 内训选项
- 按您的日期,为您的团队专场举办
本页内容16个部分
培训项目概述
International Public Sector Accounting Standards (IPSAS) are issued by the International Public Sector Accounting Standards Board (IPSASB) for use by governments and other public sector entities. They aim to improve the quality of general purpose financial reporting, so that decisions on public resources rest on complete and comparable information, and they strengthen transparency and accountability.
The standards have changed substantially in the last few years. The IPSASB’s 2026 Handbook now runs from IPSAS 1 to IPSAS 51 and includes the Board’s first sustainability standard. New standards on leases (IPSAS 43), property, plant and equipment (IPSAS 45) and measurement (IPSAS 46) took effect on 1 January 2025. IPSAS 47 Revenue, which replaces IPSAS 9, 11 and 23, and IPSAS 48 Transfer Expenses took effect on 1 January 2026, together with IPSAS 49 Retirement Benefit Plans.
More change is scheduled. IPSAS 50 on exploration for and evaluation of mineral resources applies from 1 January 2027. IPSAS 51 Tangible Natural Resources Held for Conservation and IPSASB SRS 1 Climate-related Disclosures, both issued in January 2026, apply from 1 January 2028, with earlier adoption permitted. Many training materials still teach IPSAS 9, 13, 17, 23 and 29 as current; this programme is built on the current handbook.
IPSAS Training in Tbilisi covers the full suite over five days: the Conceptual Framework and presentation, assets and measurement, revenue, expenses and liabilities, financial instruments, consolidation and the wider reporting landscape, including first-time adoption and climate disclosures. Georgia’s own move to accrual reporting under IPSAS-based rules gives the programme a practical reference point.
Sessions combine short explanations with numerical examples and journal entries, so participants practise the judgements that preparers and auditors face.
The Programme Strengthens Institutional Capability
- 将国际公共部门会计准则理事会概念框架应用于会计判断
- Presenting complete accrual-based financial statements
- Preparing cash flow statements and budget comparison statements
- Accounting policies, estimates and corrections of errors
- 根据《国际公共部门会计准则第45号》确认和计量物业、厂房和设备
- 应用IPSAS 46计量基础,包括当前运营价值
- Lessee and lessor accounting under IPSAS 43
- Revenue recognition under IPSAS 47
- Grants, subsidies and other transfers under IPSAS 48
- 社会福利、条款和员工福利
- Financial instruments under IPSAS 41
- 存货、无形资产与减值
- Service concession arrangements
- Consolidation, associates and joint arrangements
- Public sector combinations and related party disclosures
- 首次采用权责发生制国际公共部门会计准则(IPSAS)
- Long-term fiscal sustainability and service performance reporting
- 基于IPSASB SRS 1的气候相关披露
- Planning and managing an IPSAS transition
其结果是一个能够应用当前生效的标准并规划未来两年内生效的标准团队。
The Growing Importance of IPSAS
Accrual reporting based on IPSAS is spreading. The IFAC and CIPFA International Public Sector Financial Accountability Index 2025 projects that 56% of jurisdictions will report on an accrual basis by 2030, and that 81% of those will use IPSAS directly, with modifications or as the basis of national standards. By 2030, 60% of accrual-using jurisdictions are expected to be middle- or low-income economies.
处于不同发展阶段的国家展示了这一趋势。肯尼亚国家财政部于2024年公布了国家政府转向权责发生制IPSAS的行政命令,预计将于2025年6月30日结束的财年发布首份权责发生制报表。自2017年以来,沙特阿拉伯根据“2030愿景”持续推进分阶段转型。格鲁吉亚的改革始于2009年,并于2020年将其预算单位过渡到以权责发生制为基础的标准。在每个案例中,最艰难的工作都在于资产、合并和技能。
各机构日益需要具备以下能力的专业人员:
- 识别哪些标准立即适用,哪些稍后生效
- Explaining the differences between superseded and current standards
- 建立并评估完整的资产登记册
- Selecting appropriate measurement bases under IPSAS 46
- 区分有约束性安排和无约束性安排的收入
- Recognising transfer expenses consistently with IPSAS 48
- Accounting for leases on a right-of-use basis
- Applying impairment and expected credit loss requirements
- Defining the reporting entity and consolidating controlled entities
- Writing clear accounting policies and notes
- Reconciling budget execution reports with financial statements
- Preparing for audit of accrual statements
- Planning a phased transition under IPSAS 33
Strong IPSAS systems help organisations:
- Show the full cost of public services
- Make assets and liabilities visible to decision-makers
- Manage fiscal risks, including guarantees and long-term obligations
- Improve the credibility of reports to lenders and citizens
- Support audit opinions on consolidated statements
- Compare performance across entities and countries
- 规划资产维护与更换
- Meet the reporting expectations of development partners
- Prepare for climate-related disclosure
IPSAS adoption is a long reform rather than a single project. It works best when policy, systems, data and people move together, and when the finance team understands the reasoning behind each standard.
来源:IPSASB公告:2025年IPSAS 43、45、46;2026年IPSAS 47、48、49;2027年IPSAS 50;2028年IPSAS 51及SRS 1。
1. 哪个标准取代了IPSAS 23非交换交易收入?
The IPSASB states that IPSAS 47 replaces IPSAS 9, IPSAS 11 and IPSAS 23, effective 1 January 2026.
2. When does IPSASB SRS 1 Climate-related Disclosures take effect?
The IPSASB issued SRS 1 in January 2026 for periods beginning on or after 1 January 2028, with earlier adoption permitted.
3. Which standard replaced IPSAS 17 Property, Plant and Equipment from 1 January 2025?
The IPSASB's measurement package introduced IPSAS 45, replacing IPSAS 17, effective 1 January 2025.
谁应该参加本IPSAS培训?
本培训项目适合:
- Government officials and project managers responsible for IPSAS transition
- Treasury and accounting department staff of ministries of finance
- 部委、机构和市政当局的总会计师
- Finance and accounting managers of public sector entities
- Accountants and finance staff preparing financial statements
- IFRS and IPSAS implementation and maintenance teams
- Financial management specialists in project implementation units
- Finance staff of state-owned enterprises within the general government sector
- Finance officers of international organisations and NGOs reporting under IPSAS
- Staff of supreme audit institutions and internal auditors
- 公共部门标准制定者与监管机构
- Financial systems and ERP teams supporting accrual reporting
- Fiscal risk and debt management officers
- Consultants advising on IPSAS and public financial reporting
A working knowledge of accounting is helpful. Each standard is introduced from its principles before the detailed requirements.
勾选您的团队需要具备的能力。
IPSAS Training Objectives
Upon successful completion of this IPSAS Training, participants will be able to:
- Explain the IPSASB, its due process and the structure of the 2026 Handbook
- 将概念框架应用于确认和计量问题
- Prepare a complete set of IPSAS financial statements, including budget comparison
- Account for property, plant and equipment, leases and intangible assets under current standards
- Choose and apply measurement bases under IPSAS 46
- 根据IPSAS 47和IPSAS 48确认收入和转移费用
- 核算社会福利、准备金和雇员福利
- Apply IPSAS 41 to classification, measurement and impairment of financial instruments
- Determine the reporting entity and prepare consolidated statements
- Use the transitional reliefs of IPSAS 33
- Describe the requirements of IPSASB SRS 1 and upcoming standards
- Draft a practical IPSAS transition or update plan
每个目标都辅以实例,学员可以与自己的团队重新使用这些实例。
培训项目内容与结构
- Definition, purpose and brief history of IPSAS
- The IPSASB, its governance and due process
- 2026年手册:当前标准、生效日期以及被取代的标准
- 概念框架与政府会计的概念基础
- IPSAS 1 Presentation of Financial Statements
- IPSAS 2 Cash Flow Statements
- IPSAS 3 Accounting Policies, Changes in Accounting Estimates and Errors
- IPSAS 45 Property, Plant and Equipment, replacing IPSAS 17
- Heritage assets and infrastructure assets under IPSAS 45
- IPSAS 46计量:历史成本、当前运营价值、公允价值
- IPSAS 16 Investment Property
- IPSAS 31 Intangible Assets
- IPSAS 21 and IPSAS 26 Impairment of non-cash-generating and cash-generating assets
- IPSAS 12 Inventories
- IPSAS 47 Revenue, replacing IPSAS 9, IPSAS 11 and IPSAS 23
- Binding arrangements, compliance obligations and revenue without binding arrangements
- Taxes, fines and transfers received
- IPSAS 48 Transfer Expenses: grants and subsidies paid
- IPSAS 42 Social Benefits
- IPSAS 19 Provisions, Contingent Liabilities and Contingent Assets
- IPSAS 39 Employee Benefits and IPSAS 49 Retirement Benefit Plans
- IPSAS 34 Separate Financial Statements
- IPSAS 35 Consolidated Financial Statements and the control assessment
- IPSAS 36 Investments in Associates and Joint Ventures
- IPSAS 37 联合安排
- IPSAS 38 Disclosure of Interests in Other Entities
- IPSAS 40 公共部门合并
- IPSAS 18 Segment Reporting
- RPG 1 Reporting on the Long-Term Sustainability of an Entity’s Finances
- RPG 2 Financial Statement Discussion and Analysis
- RPG 3 Reporting Service Performance Information
- IPSASB SRS 1 Climate-related Disclosures, effective 2028
- IPSAS 51 Tangible Natural Resources Held for Conservation and IPSAS 50 mineral resources
- The Cash Basis IPSAS and its role in transitions
- 权责发生制财务报表审计及与最高审计机关的合作
完整的每日课程内容
本课程遵循财务报表的逻辑,从框架到资产、收入与负债、集团,最后到更广泛的报告议程。
- Day 1: Framework, presentation and first-time adoption
- Day 2: Assets, leases and measurement
- Day 3: Revenue, transfers, liabilities and financial instruments
- Day 4: Reporting entity, consolidation and disclosures
- Day 5: Performance, sustainability reporting and transition planning
完整的每日课程内容
第一天 | 框架、演示与首次采纳
- Definition, purpose and brief history of IPSAS
- The IPSASB, its governance and due process
- 2026年手册:当前标准、生效日期以及被取代的标准
- 概念框架与政府会计的概念基础
- IPSAS 1 Presentation of Financial Statements
- IPSAS 2 Cash Flow Statements
- IPSAS 3 Accounting Policies, Changes in Accounting Estimates and Errors
- IPSAS 14 报告期后事项
- IPSAS 24 财务报表中预算信息的列报
- IPSAS 33 First-time Adoption of Accrual Basis IPSAS
案例研究:格鲁吉亚从收付实现制向权责发生制的转型之路
Participants review the published account of Georgia’s reform: a reform programme dating from 2009, accrual-based standards for central entities from 2020 and municipalities from 2021, and remaining gaps such as an incomplete asset registry and unaudited consolidated statements. Teams map these steps to IPSAS 33 reliefs and identify which choices they would repeat or change.
Second Day | Assets, Leases and Measurement
- IPSAS 45 Property, Plant and Equipment, replacing IPSAS 17
- Heritage assets and infrastructure assets under IPSAS 45
- IPSAS 46计量:历史成本、当前运营价值、公允价值
- IPSAS 16 Investment Property
- IPSAS 31 Intangible Assets
- IPSAS 21 and IPSAS 26 Impairment of non-cash-generating and cash-generating assets
- IPSAS 12 Inventories
- IPSAS 43 Leases: right-of-use model for lessees, replacing IPSAS 13
- IPSAS 44 Non-Current Assets Held for Sale and Discontinued Operations
- IPSAS 32服务特许权安排:授予方
Workshop: Building an Opening Asset Register
利用缺少成本且记录杂乱的部委固定资产清单,团队对资产进行分类,根据IPSAS 46选择计量基础,估算专业建筑当前的运营价值,并根据IPSAS 43确认租赁车队。该练习反映了格鲁吉亚官员报告的一个难点,即由于重估需要资金,财产和设备标准是最难实施的。
Third Day | Revenue, Transfers, Liabilities and Financial Instruments
- IPSAS 47 Revenue, replacing IPSAS 9, IPSAS 11 and IPSAS 23
- Binding arrangements, compliance obligations and revenue without binding arrangements
- Taxes, fines and transfers received
- IPSAS 48 Transfer Expenses: grants and subsidies paid
- IPSAS 42 Social Benefits
- IPSAS 19 Provisions, Contingent Liabilities and Contingent Assets
- IPSAS 39 Employee Benefits and IPSAS 49 Retirement Benefit Plans
- IPSAS 41 Financial Instruments, replacing IPSAS 29
- 国际公共部门会计准则(IPSAS)第28号和第30号:金融工具的列报与披露
- IPSAS 4 The Effects of Changes in Foreign Exchange Rates
Workshop: Applying IPSAS 47 and IPSAS 48 to Real Transactions
Teams work through a set of transactions: a tax assessment, a donor grant with conditions, a fee-based service contract, a capital transfer to a municipality and a subsidy paid to a public company. For each they decide whether a binding arrangement exists, when revenue or expense is recognised and how the entry differs from the old IPSAS 23 treatment.
Fourth Day | Reporting Entity, Consolidation and Disclosures
- IPSAS 34 Separate Financial Statements
- IPSAS 35 Consolidated Financial Statements and the control assessment
- IPSAS 36 Investments in Associates and Joint Ventures
- IPSAS 37 联合安排
- IPSAS 38 Disclosure of Interests in Other Entities
- IPSAS 40 公共部门合并
- IPSAS 18 Segment Reporting
- IPSAS 20 关联方披露
- IPSAS 22 Disclosure of Financial Information about the General Government Sector
Case Study: Consolidating Central Government
The IMF reported that Georgia’s Treasury has published consolidated central government statements under 24 accrual-based IPSAS since 2021, but that these were not audited by the State Audit Office, and Georgian officials noted that administered items were still excluded. Using a simplified group of ministries, agencies and public companies, teams assess control, prepare consolidation adjustments and draft the disclosures an auditor would expect to see.
Fifth Day | Performance, Sustainability Reporting and Transition Planning
- RPG 1 Reporting on the Long-Term Sustainability of an Entity’s Finances
- RPG 2 Financial Statement Discussion and Analysis
- RPG 3 Reporting Service Performance Information
- IPSASB SRS 1 Climate-related Disclosures, effective 2028
- IPSAS 51 Tangible Natural Resources Held for Conservation and IPSAS 50 mineral resources
- The Cash Basis IPSAS and its role in transitions
- 权责发生制财务报表审计及与最高审计机关的合作
- Systems, chart of accounts and data requirements for IPSAS
- IPSAS adoption experience around the world
Capstone Exercise: An IPSAS Update and Transition Roadmap
Each team prepares a 24-month roadmap for a public entity that reports under older IPSAS. The plan covers the move to IPSAS 43, 45, 46, 47 and 48, readiness for SRS 1, asset data, system changes, staff training and audit engagement. Teams present their plans and receive feedback on sequencing, risks and resources.
国际公共部门会计准则(IPSAS)培训方法
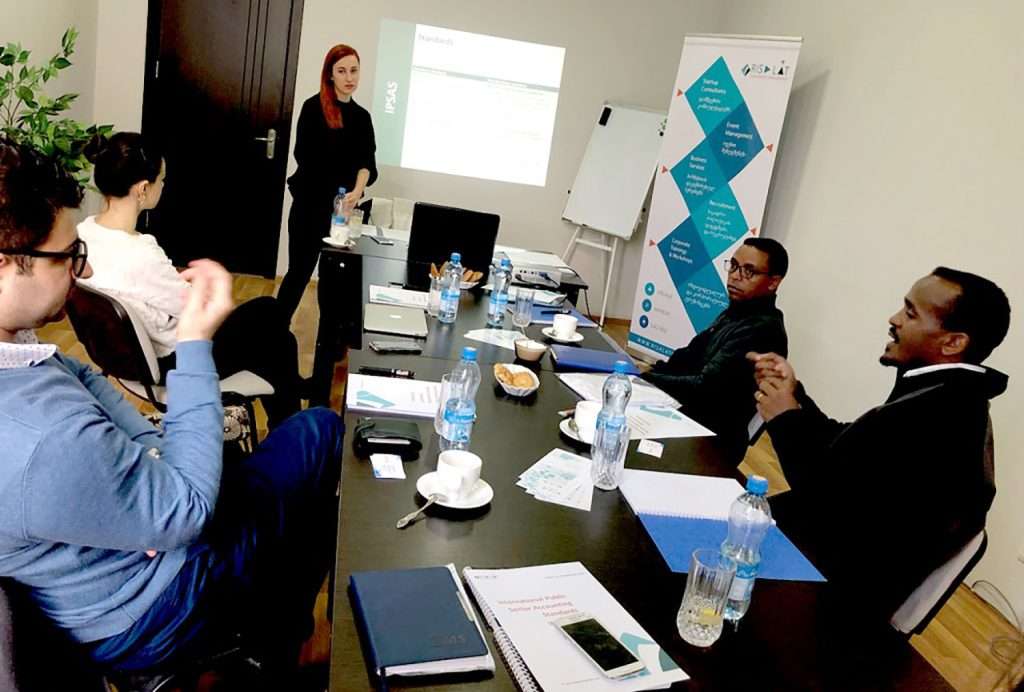
The programme is interactive and practical, combining direct instruction with numerical work and analysis of real reforms.
本培训项目融合了:
- Concise expert briefings on each standard
- Comparisons of superseded and current requirements
- 带计算过程的示例和日记账分录
- 关于计量和合并的电子表格练习
- Case studies from published reform reports
- Small-group problem solving
- Drafting of accounting policies and note disclosures
- 团队成果同伴互评
- Discussion of participants’ own transition challenges
- Daily knowledge checks
- A capstone roadmap for each participant’s institution
Participants are encouraged to bring questions from their own entities so the discussion addresses the standards they actually apply.
预期成果
Upon completion of this IPSAS Training, participants will be able to:
- State which IPSAS are current and when new ones take effect
- Prepare and review a full set of accrual-based statements
- Apply IPSAS 45 and IPSAS 46 to asset recognition and measurement
- Account for leases under IPSAS 43
- Apply IPSAS 47 and IPSAS 48 to revenue and transfers
- Apply IPSAS 41 to financial instruments
- Prepare consolidation adjustments for public sector groups
- Explain the purpose and main requirements of SRS 1
- Lead or contribute to an IPSAS transition plan
学员将带走检查清单、实例解析以及可与管理层和审计人员探讨的行动路线图。
每位学员£2,880 · 发票与银行转账 · 5人及以上团体可享折扣
同一机构五人及以上:请在申请发票时索取团体价。
Ten or more: an in-house version for your institution may cost less per person. Ask for an in-house quote.
注册截止于 44天后 (2027年1月6日)
Institutional Application of IPSAS Training
本培训项目帮助机构加强:
- Accounting policy manuals
- Charts of accounts mapped to IPSAS
- 资产登记册与估值流程
- Revenue and grant recognition procedures
- Liability and provision reporting
- 合并流程与集团报告
- Budget-to-accounts reconciliation
- 审计准备与跟进
- Fiscal risk disclosure
- Readiness for sustainability reporting
- 各部委和市镇的会计能力
学员将带着实用工具回到工作岗位,以提升:
- IPSAS effective dates and transition checklist
- IPSAS 47和IPSAS 48决策树
- IPSAS 46计量基础选择器
- 租赁识别与使用权模板
- Opening asset register template
- 合并工作表
- 附注披露检查清单
- 转型路线图模板
Institutions planning a transition can begin with Risalat’s free institutional capacity assessment or governance audit to identify priorities.
区域相关性与应用
欧洲
Georgia’s Ministry of Finance hosted a PEMPAL treasury study visit in Tbilisi in May 2025, attended by more than 70 officials from 16 countries across Europe and Central Asia. Georgian presenters reported 26 IPSAS-based standards in use at central and subnational level and the first audit of financial statements by the supreme audit institution in 2025, while noting gaps in consolidation and asset data.
非洲
Kenya’s National Treasury approved the national government’s transition to accrual IPSAS in 2024 and set workstreams for chart of accounts revision, IFMIS changes, asset and liability valuation and capacity building. Similar transitions across Africa create strong demand for practical skills in IPSAS 45, 46 and 47.
中东
A World Bank account of a 2022 regional webinar reported that 11% of MENA member jurisdictions had fully adopted IPSAS and 53% had partially adopted them, with Saudi Arabia pursuing a phased transition since 2017 under Vision 2030. Entities in the region now need to update to the standards issued since then.
亚洲
哈萨克斯坦、吉尔吉斯共和国、塔吉克斯坦和乌兹别克斯坦参加了2025年第比利斯考察访问,反映了中亚积极的国库和会计改革。IFAC和CIPFA指数预计,到2030年,大多数新的权责发生制采用者将是中低收入经济体,其中许多在亚洲和非洲。
The programme draws on these experiences so participants can compare their own reform path with peers.
东道国概况:格鲁吉亚
Tbilisi, Georgia’s capital, offers modern business venues, a wide choice of hotels and moderate costs, with a historic centre that makes evenings pleasant for visiting delegations.
Georgia is a relevant benchmark for IPSAS. The Treasury Service of the Ministry of Finance leads the reform, maintains a unified chart of accounts across central and local budget entities and publishes financial statements annually. Georgia ranked first of 125 countries for budget transparency in the 2023 Open Budget Survey with a score of 87, according to the Ministry of Finance. Its remaining challenges, including asset registers and consolidation, mirror those of many participants.
Tbilisi International Airport has regular flights from Europe, the Middle East and Central Asia. Citizens of many countries can visit Georgia without a visa for short stays, and others can apply for an e-visa or a visa in advance. Participants should confirm current rules with the Ministry of Foreign Affairs of Georgia; Risalat provides visa support letters on request.
IPSAS Training Deliverables
Participants receive a complete package of preparation, learning materials and follow-up support built on the current IPSASB Handbook.
培训开始前
- 学员课前评估
- IPSAS Readiness Assessment
- IPSAS Resource Pack
- 课前阅读资料
- 免费签证支持与咨询
培训期间
- 机场接机与欢迎协助
- Accommodation with breakfast: 6 nights, check-in Sunday 14 February 2027, check-out Saturday 20 February 2027 (one night before and one night after the programme)
- 欢迎交流晚宴
- Risalat培训礼包(背包、水瓶、马克杯、T恤、帽子、护照套、笔、笔记本、冰箱贴及钥匙扣)
- Comprehensive IPSAS Training Manual
- IPSAS Effective Dates and Transition Checklist
- IPSAS 47 and IPSAS 48 Decision Trees
- IPSAS 46 Measurement Basis Selector
- Lease Identification and Right-of-Use Template
- Opening Asset Register Template
- Consolidation Worksheet
- Note Disclosure Checklist
- 实践研讨与模拟演练
- 小组讨论与同伴学习
- 每日午餐与茶歇
- 全面使用培训场地设施
- 装有数字学习资料的迷你平板电脑
- 实地考察(如适用)
- 城市休闲观光
培训结束后
- 结业证书
- Risalat培训项目参与表彰奖
- 培训后参考资料
- IPSAS过渡路线图模板
- Summary of Upcoming IPSAS and SRS Requirements
- Worked Example Workbook
- 培训后支持与跟进指导
- 培训项目报告
Ministries of finance, treasuries, audit institutions and project units can request a tailored in-house version of this programme focused on their own standards, systems and timelines. Please request a proposal to discuss your needs.
Common Challenges in IPSAS, And How This Training Helps
How can teams know which IPSAS are current?
Many manuals still cite IPSAS 9, 13, 17, 23 and 29, which have been replaced. Day 1 sets out the 2026 Handbook, effective dates and what each new standard replaced.
How can entities value assets when records are incomplete?
Missing asset data is one of the most common obstacles, as Georgia’s reform shows. Day 2 covers IPSAS 45, IPSAS 46 and the IPSAS 33 reliefs for opening balances.
How should revenue and grants be recognised under IPSAS 47?
新标准用对有约束力安排的关注取代了交换与非交换的划分。第3天研讨会将其实际应用于税收、补助和服务合同。
How can government bring leases onto the balance sheet?
IPSAS 43 requires a right-of-use model for lessees. Day 2 shows how to identify leases and measure assets and liabilities.
How can central government produce consolidated statements an auditor can rely on?
Day 4 covers control assessment, consolidation adjustments and disclosures, using the general government perimeter issues reported for Georgia as a case.
公共实体应如何为气候相关披露做准备?
SRS 1 applies from 2028 with early adoption permitted. Day 5 explains its requirements and the governance and data work needed now.
How can a transition be planned without stopping daily operations?
The Day 5 capstone builds a phased roadmap that sequences policies, systems, data and training.
常见问题
Is the programme based on the latest IPSAS?
Yes. It follows the IPSASB 2026 Handbook, including IPSAS 43, 45 and 46 (effective 2025), IPSAS 47, 48 and 49 (effective 2026), IPSAS 50 (2027), and IPSAS 51 and SRS 1 (2028).
Which old standards are no longer taught as current?
IPSAS 9、11和23被IPSAS 47取代;IPSAS 13被IPSAS 43取代;IPSAS 17被IPSAS 45取代;IPSAS 29被IPSAS 41取代。该项目阐释了这些变更,以便团队更新其政策。
Is it suitable for entities still on the cash basis?
Yes. Day 1 covers IPSAS 33 first-time adoption and Day 5 covers the Cash Basis IPSAS and transition planning.
Does the programme cover climate reporting?
Yes. Day 5 introduces IPSASB SRS 1 Climate-related Disclosures, issued in January 2026 and effective for periods beginning on or after 1 January 2028.
能否以内训形式举办?
可以。国库、部委、审计机构和项目单位可以申请专注于其自身标准和系统的定制版本。
Who Will Deliver This Programme
Each date is delivered by a team assigned from Risalat's expert network for this subject. For this programme we assign:
How we choose them: Experience in the region of the participants or comparable settings; Command of the financier rules that apply (World Bank, ADB, AfDB, EU, UN) where relevant; Delivery in English; other languages on request for in-house groups; No conflict of interest with participants' institutions.
Training courses in Tbilisi会计与财务培训课程
为何选择在第比利斯举办本培训项目
第比利斯以公共服务大厅和反腐败改革而闻名,并对许多国家提供便利的签证政策。
The International Public Sector Accounting Standards Training in Tbilisi programme in February 2027 brings together officials and professionals from across the Caucasus region and beyond. Sessions combine short inputs, case studies and group work on participants' own files, and the city's institutions can be added as a study visit on request.
交通:第比利斯国际机场(TBS)。
使用免费的签证查询工具确认您是否需要签证,完成报名后即可申请邀请函。
其他城市的同主题培训
- Mini Degree in Climate Finance and Resilience in Copenhagen (Copenhagen)
- Mini Degree in Donor-Funded Project Management in Dubai (Dubai)
- Carbon Accounting and Net-Zero Planning for Institutions in Kuala Lumpur (Kuala Lumpur)
- Sustainable Finance and Green Taxonomies in Nairobi (Nairobi)
- Mini Degree in Public Financial Management in London (London)
- AI for Human Resources, Payroll and Workforce Planning Training in Amsterdam (Amsterdam)
第比利斯的其他培训项目
- Performance Management in Government in Tbilisi
- Mountain Highway Slope Protection and Mudflow Barrier Engineering in Tbilisi
- Hydro Plant Electro-Mechanical Refurbishment and Turbine Rehab in Tbilisi
- Modern Irrigation Scheme Modernisation and Water Conveyance Systems in Tbilisi
- Secondary Road Rehabilitation and Climate-Proof Pavement Design in Tbilisi
Teams often travel here from Azerbaijan, Georgia, Armenia, Ukraine, Moldova, Albania, Serbia, North Macedonia. Funding, visa letters and group rates are explained on each country page.
- PEFA:公共支出与财政问责 PEFA秘书处
- 经济合作与发展组织(OECD) OECD
For teams and institutions
Bring your team
Teams that learn together apply more at work. Tell us how many people and how you would like to take part: we reply with a group quote within two working days.
Watch: this programme in short

Other dates and cities for this subject: IPSAS, IFRS and Public Sector Accounting training courses (13 upcoming dates).
格鲁吉亚更多培训课程 · 亚洲所有培训项目 · 完整培训日历
在路线图中规划此项目:为什么重要、为什么要批准它、要计划的日期以及它所构建的职业生涯。